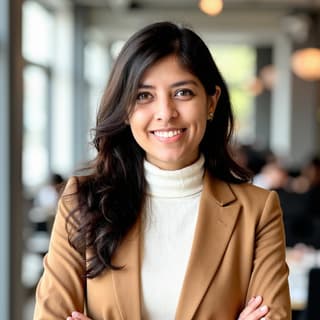


Work with Hiteeksha
About
Hiteeksha also coaches for Quantitative Finance and AI for Finance. View all.
Hiteeksha’s Asset Management Qualifications
Experience level: Vice President
60+ Asset Management clients
I'm a VP in the multi-asset strategies group at BlackRock, where I work as a Quantitative Researcher on systematic investing, portfolio risk, AI and optimization. Before this, I worked in risk advisory at Ernst & Young and in fixed income research at Western Asset Management, and as a Product manager for a financial advisor tool at BlackRock. I've seen asset management from the research side, the risk side, and the client side. I hold a Master of Financial Engineering (MFE) from UCLA Anderson, an MBA in Finance, Bachelors' in IT Engineering and the FRM charter. I also didn't start out as a quant. I moved through consulting and risk roles first, then found my way into quant research later than most people in this field do. That's part of why I coach: I know what it's like to build toward asset management without a clear map, and I can help you figure out yours - whether that means breaking in, positioning the experience you already have, or understanding what the day-to-day work is actually like.
Hiteeksha can help with:
Application Strategy
Interview Prep
Resume Review
Work Experience

Board Member
UCLA Women
November 2025 - Present
Educator
‘Quant’ify Your Career
September 2024 - Present
Career Guidance & Mentorship Platform to educate and share experiences & learnings in Quantitative Finance and Professional Development
Angel Investor
Hustle Fund
February 2024 - December 2024
Quantitative Research
BlackRock
September 2022 - Present
Quant Research-Multi Asset Strategy Quantitative Finance, Python and +3 skills
Product Manager
BlackRock
April 2021 - September 2022
Aladdin Advisor Center Software Product Management, Product Planning and +2 skills
Research Assistant
UCLA Anderson
August 2020 - December 2020
1. Project with Professor Mariko Sakakibara: Analysing factors like earnings volatility and forecast errors affecting information asymmetry in a firm - leading to a corporate spinoff. 2. Project with Global Economics Management PhD student Thomas Groesbeck: Quantifying costs and benefits of early access software by analysing bug reports using Web Scraping & Natural Language Processing. Quantitative Finance
Software Engineering Intern
Western Asset Management
May 2020 - July 2020
AI in Bond Fund management
Risk Analyst
BlackRock
February 2018 - August 2019
Quant and AI Financial risk analyst for wealth manager clients
Consultant
EY
May 2016 - February 2018
Financial Risk Advisory for banks

Intern
Karvy Stock Broking
May 2015 - August 2015
Currency Derivatives Desk
Education
Narsee Monjee Institute of Management Studies
MBA (Dual Degree), Finance
2011 - 2016
Narsee Monjee Institute of Management Studies
Bachelor's (Dual Degree), Engineering in Information Technology
2011 - 2016
UCLA Anderson School of Management
Master of Financial Engineering
Coursework: Econometrics, Quantitative Asset Management, Computational Finance, Machine Learning, Financial Risk, Fixed Income, Derivatives, Stochastic Calculus
Hiteeksha doesn’t have any offerings in this category yet.
Hiteeksha also coaches for Quantitative Finance and AI for Finance. View all.
No posts yet
When Hiteeksha posts, it will show up here.